How to raise cash without selling your gold
Need cash but don't want to sell your metal? How gold- and silver-backed financing works, three real transactions and the risks involved.
The dilemma: you need cash, but you don't want to sell
It is one of the most common dilemmas for anyone who holds investment metals: you need cash, but selling doesn't make sense. Selling means unwinding a position built with care, taking the tax hit on the disposal and, often, giving up a rise in value you believe is still to come. And yet you need the money now.
Metal-backed financing resolves exactly that tension. At Andorra Metals we help you access it through RealWorld.fi, a platform that specialises in providing liquidity against physical assets. Below we explain what it is, how it works and what to bear in mind before using it.
What exactly is it?
It is not a traditional bank loan. You place your metal in insured custody, a digital token representing it is issued, and that token is transferred to a funder under a repurchase agreement with a fixed date. In return you receive cash straight away. On the agreed date you buy the token back and get your metal back. The key difference from selling: you don't give up your position. You get it back in full when you repay, and you can do so early with no penalty.
You don't sell your metal: you pledge it as collateral, receive cash and get it back in full when you repay.
Three real transactions
The service works for different ways of holding wealth in metal. Here are three real examples, on a gold bar, a gold coin and silver:
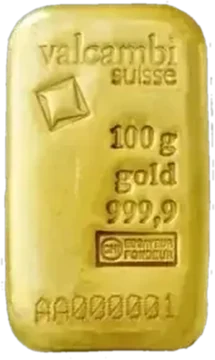
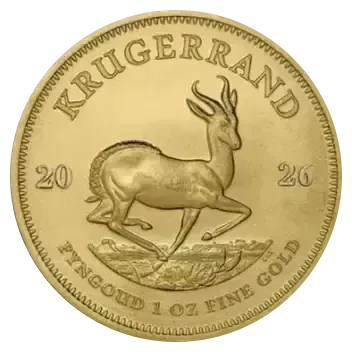
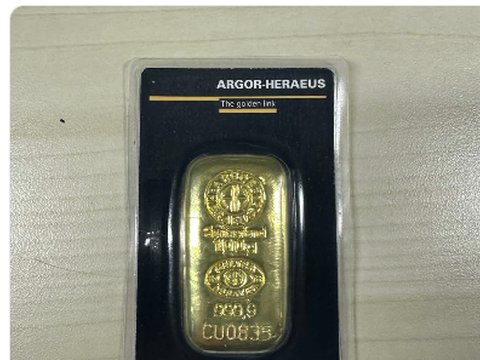 100 g gold barArgor-Heraeus · 999.9 | 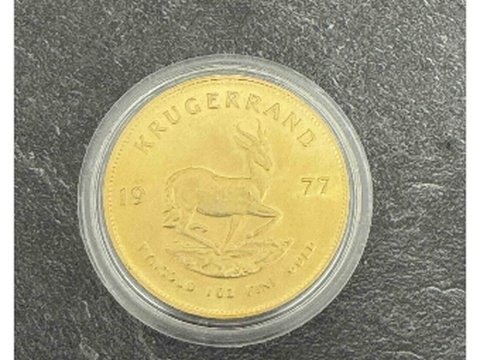 1 oz gold coinKrugerrand · 916.7 | 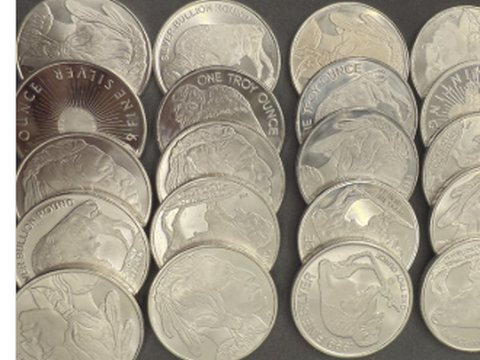 Silver 20 × 1 ozCoins · 999 | |
|---|---|---|---|
| Valuation | $13,841 | $4,306 | $1,315 |
| Cash received | $11,158 | $2,650 | Depending on offer |
| Of value | 80% (max.) | ≈ 62% | 50–70% |
| Term | 365 days | 90 days | Your choice |
| Interest | 10% a year | 13% a year | Depending on terms |
| Custody | Geneva (GPM / Loomis) | Third party (EU) | Miami (UOVO) |
Amounts in US dollars, as shown on the platform. Terms of each specific transaction; not an offer.
With that cash each client covers what they need — an opportunity, a one-off payment, a cash-flow gap — without selling a gram of metal, and gets it back when they repay.
An important point about the first case: the amount received is 80% of the valuation, the top of the range. The higher that percentage, the less headroom there is and the more important it is to be certain you can buy back on time. For most people the prudent choice is to stay in the 50% to 70% band, which leaves more of a cushion, as in the other two cases.
How it works, step by step
- 01Tell us what you have
Describe the metal you want to raise cash against and we will give you an initial estimate.
- 02Valuation and custody
The asset is authenticated and valued by experts and placed in insured custody. You receive a valuation and the available financing range.
- 03Choose your terms and receive the funds
You set the amount and the term (from 30 days to 12 months) and receive the cash, usually within a couple of days.
- 04Repay and get your metal back
You can repay early with no penalty. Once repayment is complete, your asset is returned in the same condition.
What you should know before signing up
- The buy-back date is firm. If you don't buy back within the agreed term, the funder keeps all of the metal, and the difference between its value and the amount you received is not refunded. There is very little leeway after maturity. It only makes sense if you are reasonably certain you can repay on time.
- There are no margin calls. A fall in the metal price during the term does not require you to add collateral or trigger a liquidation. The only risk event is failing to buy back on time. For anyone who expects the metal to rise in value, this is an advantage.
- The metal is held by third parties. The asset is deposited in insured facilities run by professional custodians. Check the location and specific terms before signing up.
- There are tax implications. Because the transaction involves a transfer and a later buy-back, it may have tax consequences in your country of residence. You must check with your adviser before going ahead.
- It is not a regulated product. The service is not supervised by the AFA (Andorra's financial authority) or covered by any Andorran guarantee fund.
Who it suits
- You need cash for a defined period.
- You are reasonably certain you can repay on time.
- You don't want to unwind your metal position.
- Your cash flow is tight and you're not sure you can buy back.
- You want the maximum possible amount at any price.
- You need a regulated, guaranteed product.
In short
Metal-backed financing lets you turn an idle asset into cash without selling it, while keeping the option to get it back in full. Used well — with a prudent amount and the certainty that you can repay — it is a useful tool for anyone whose wealth is held in metal and who needs cash-flow flexibility.